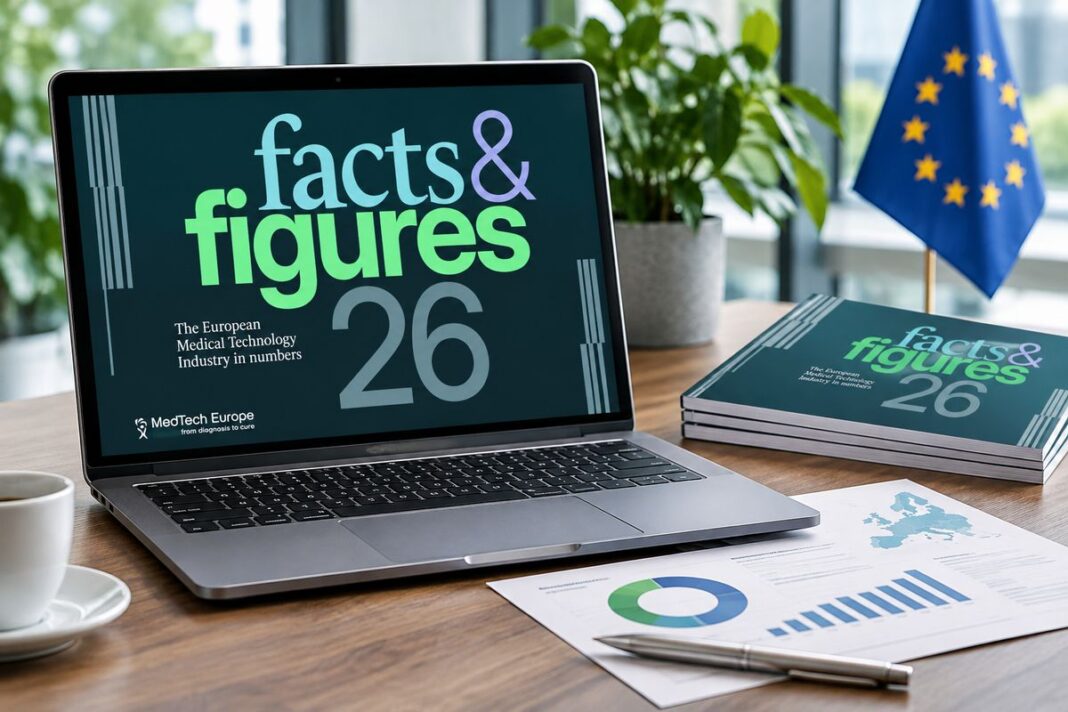
MedTech Europe’s Facts & Figures 2026 report estimates the European medical technology market at €173 billion in 2025. Although the sector continues to expand its workforce and maintain strong patent activity, market growth has slowed to 1.8%, while Europe’s share of the global market has fallen to 25.6%.
The annual report, published on 6 October 2026, examines the economic footprint, employment, innovation, healthcare expenditure and international trade of the European medical technology industry.
European market growth slows to 1.8%
The European medical technology market reached approximately €173 billion in 2025. Its growth rate of 1.8% was considerably below the average annual growth of 5.6% recorded over the previous decade.
Europe accounted for 25.6% of the global medical device market in 2025, down from 26.4% in 2024 and approximately 29% in 2015. The United States remained the largest market, with a 47.6% share.
Germany represented 24.6% of the European market, followed by the United Kingdom (12.9%), France (12.4%), Italy (9.4%) and Spain (7.0%).
Medical technologies account for approximately 7.3% of total healthcare expenditure in Europe, equivalent to less than 1% of regional GDP. Annual expenditure is estimated at approximately €325 per capita. Medical devices, including imaging technologies, account for 6.7% of healthcare expenditure, while in vitro diagnostics (IVDs) represent 0.6%.
Employment exceeds 950,000
The European medical technology industry directly employs more than 950,000 people, compared with over 930,000 reported in the previous edition.
Germany has the largest workforce, with 212,100 employees, followed by the United Kingdom (158,500) and Italy (133,627). Ireland and Switzerland have the highest employment density relative to population, with 92 and 79 employees per 10,000 inhabitants, respectively.
The sector accounts for approximately 0.37% of total European employment. Value added per employee is estimated at around €182,000.
For comparison, the European pharmaceutical industry employs approximately 955,000 people, placing the two sectors at a similar level of direct employment.
First reported decline in the number of companies
The report identifies more than 36,000 medical technology companies in Europe, compared with over 38,000 in the 2025 edition. This represents the first year-on-year decline recorded in the report.
MedTech Europe notes that the change is driven largely by developments in Germany, where company numbers have fluctuated significantly in previous editions. The association advises caution when interpreting year-on-year changes because the figures are collected through national industry associations.
Small and medium-sized enterprises (SMEs) account for approximately 90% of the industry. Most of these companies employ fewer than 50 people.
The report highlights the exposure of smaller businesses to rising regulatory compliance costs and restrictive purchasing practices, particularly in the context of the ongoing revision of the EU Medical Devices Regulation (MDR) and In Vitro Diagnostic Medical Devices Regulation (IVDR).
Medical technology leads in patent grants
Research and development remains a major feature of the European medical technology sector. Industry-wide R&D expenditure is estimated at 6.5–7% of annual sales, rising to approximately 10% among the 100 largest companies.
In 2025, 15,905 patent applications in medical technology were filed with the European Patent Office (EPO), representing a 1.3% increase compared with 2024. The sector accounted for 7.9% of all EPO applications and ranked fourth among technical fields.
Medical technology recorded 12,310 granted patents in 2025, the highest number among all technical fields covered by the report.
The ratio of granted patents to applications reached 77.4%, compared with 38.6% in pharmaceuticals and 21.5% in biotechnology.
The report also estimates that more than two million medical technologies are available on the market, covering over 7,000 generic device groups.
European medical technology trade records a €4 billion surplus
Europe recorded a positive medical devices trade balance of €4 billion in 2025, excluding intra-European trade.
The United States was the leading export destination, accounting for 36.8% of European medical device exports. China represented 10.6%, followed by Japan at 5.0%.
On the import side, the United States accounted for 42.2% of supplies to the European market, while China represented 20.3%. Japan was the third-largest supplier, with a 5.7% share, followed by Mexico at 5.0%.
MedTech Europe substantially revised its Harmonised System (HS) trade code methodology in 2025–2026, expanding the coverage from 45 to more than 70 codes focused on final goods. Historical data were recalculated using the revised methodology.
Consequently, the €4 billion surplus reported for 2025 is not directly comparable with the €5 billion figure published in the previous edition.
Regulatory developments remain a key industry issue
In its assessment of the sector’s outlook, MedTech Europe identifies the revision of the MDR and IVDR as an important opportunity to improve regulatory predictability and market access while maintaining patient protection.
The association also highlights the growing complexity of requirements affecting digital medical technologies, particularly solutions incorporating artificial intelligence. These products may need to comply simultaneously with medical device legislation, the EU AI Act, data protection requirements, cybersecurity rules and the European Health Data Space framework.
The report’s findings point to a combination of continued innovation and employment growth alongside slower market expansion, a declining global market share and changes in the number of European companies.